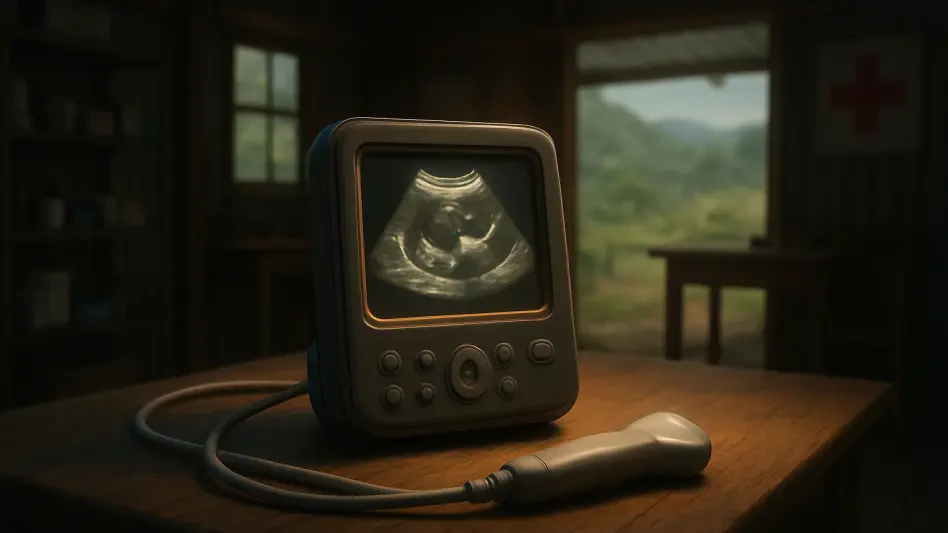
While large cart-based systems remain necessary for deep-tissue diagnostics, handheld devices are beginning to dominate high-volume point-of-care applications. The medical imaging landscape is currently undergoing a transformative shift from traditional, centralized radiology departments toward a decentralized, patient-centric model that prioritizes immediate results at the bedside. At the forefront of this evolution is the handheld ultrasound device market, which utilizes compact, portable diagnostic tools that allow healthcare professionals to visualize internal anatomy with unprecedented ease. This technological revolution is driven by the rapid integration of artificial intelligence and cloud computing, turning what were once bulky, stationary machines into pocket-sized instruments that function seamlessly with smartphones and tablets. This shift represents a fundamental change in clinical workflows, significantly reducing the time to diagnosis and improving patient outcomes across various medical settings, including emergency medicine and rural primary care. By enabling real-time assessments during standard physical exams, these devices enhance clinical efficiency and lower the overall cost of healthcare delivery for diverse populations. As the industry moves away from isolated radiology suites, the handheld ultrasound is rapidly becoming an essential tool for every modern medical practitioner.
Economic Trajectory: Financial Projections and Market Momentum
The economic outlook for handheld ultrasound devices reflects a steady and robust growth pattern, with the global market estimated at approximately $324.16 million at the start of the 2025 fiscal period. Financial projections indicate that this valuation will climb to $566.97 million by 2035, representing a healthy compound annual growth rate of 5.75% for the period spanning from 2026 to 2035. This financial momentum is fueled by the significant time savings these devices offer to busy clinical environments, as current research suggests they can reduce diagnostic decision-making time by 30% to 50% in critical hospital departments. In a healthcare economy where time-to-treatment is a primary metric for operational success, this efficiency translates into both improved patient health and significant long-term cost savings for large hospital systems and private practices alike. The ability to perform rapid scans without transporting patients to imaging centers has fundamentally changed how facilities allocate their limited resources and personnel.
Within this growing sector, wireless handheld instruments are experiencing even more aggressive expansion, boasting a specific growth rate of 9.20% as clinicians move toward more flexible hardware options. This trend signals a clear market preference for cable-free solutions that simplify disinfection processes and improve total clinician mobility in high-pressure environments like emergency rooms or intensive care units. As global healthcare systems continue to prioritize operational efficiency and cost-effectiveness, the adoption of these ultra-portable tools is expected to accelerate significantly over the coming decade. The transition toward value-based care models further incentivizes the use of point-of-care tools that can provide high-quality data at a fraction of the cost of traditional cart-based infrastructure. Manufacturers are responding to this demand by producing more durable and affordable units that can withstand the rigors of daily clinical use while maintaining the diagnostic precision required by modern medical standards.
Regional Dynamics: Global Adoption and Healthcare Infrastructure
The adoption of handheld ultrasound technology varies significantly by region, influenced by local healthcare infrastructure, regulatory environments, and institutional investment levels. North America currently dominates the global market with a 38.10% total share, driven by a highly sophisticated healthcare system and heavy capital investment in telemedicine initiatives across the United States and Canada. The US market alone is projected to reach over $150 million by 2035, reflecting a deep-seated culture of early technology adoption and a strong push toward decentralized diagnostics. In Europe, the focus remains on integrating these portable devices into existing diagnostic frameworks to streamline patient throughput and reduce the burden on overstretched radiology departments. European healthcare providers are increasingly viewing handheld units as a primary triage tool that can help identify high-risk cases before they require more expensive and time-consuming imaging procedures.
Meanwhile, the Asia-Pacific region is identified as the fastest-growing market in the world, with a projected growth rate of 6.96% as countries like China and India expand their hospital networks and seek diagnostic solutions for vast rural populations. In these emerging markets, handheld ultrasound is being used strategically to bypass the high logistical and financial costs of installing conventional imaging equipment in remote areas where traditional infrastructure is often entirely lacking. These portable solutions provide high-quality diagnostic capabilities in resource-limited environments, allowing doctors to perform screenings that were previously impossible without significant patient travel. Similarly, across Latin America, the Middle East, and parts of Africa, the technology is serving as a critical bridge for healthcare equity. By empowering local practitioners with mobile imaging tools, these regions are significantly improving maternal health outcomes and trauma response times in areas that have historically been underserved by the global medical community.
Industry Trends: The Impact of the Smartphone Revolution
Several distinct trends are defining the current decade for handheld ultrasound technology, most notably the universal adoption of point-of-care diagnostics across multiple medical disciplines. Imaging is moving from the “basement” of hospitals to the literal front lines of patient contact, with over 60% of modern units designed to interface directly with mobile devices and cloud platforms. This “smartphone revolution” allows for immediate data sharing and remote consultations via advanced telemedicine networks, bridging the physical gap between general practitioners and specialists regardless of their location. The ability to stream live ultrasound feeds to a specialist hundreds of miles away has revolutionized the way rural clinics handle complex diagnostic questions. This connectivity ensures that patients receive expert-level care without the need for unnecessary transfers to metropolitan medical centers, thereby reducing the strain on the broader healthcare system.
Beyond the traditional hospital setting, the expansion of home care and the integration of artificial intelligence-enhanced workflows are making these diagnostic tools more accessible than they have ever been in history. Artificial intelligence now helps guide non-specialist users to capture high-quality images and automates complex measurements, significantly reducing the historical barrier to entry for clinicians who are not trained sonographers. Additionally, the rise of affordable 2D solutions ensures that even small primary care practices or community clinics can provide advanced imaging services, further democratizing access to modern healthcare for the general public. As these devices become more intuitive, they are increasingly being used for chronic disease management, allowing patients to be monitored in the comfort of their own homes. This shift toward proactive and preventative imaging is expected to lead to earlier interventions and better long-term health outcomes for patients with cardiovascular and respiratory conditions.
Technological Drivers: Innovations in Transducer Design
The primary catalyst for current market expansion is the ongoing decentralization of care, which empowers clinicians to perform heart, vascular, and abdominal scans instantly during a standard physical examination. Innovation is currently led by sophisticated products such as the GE HealthCare Vscan Air SL, which features dual transducers for comprehensive studies, and the Butterfly iQ3, which utilizes advanced semiconductor technology to offer high-resolution imaging at a lower cost than traditional crystal-based probes. These advancements are turning the ultrasound probe into a “digital stethoscope” that fits conveniently in a clinician’s pocket, ready to be deployed at a moment’s notice. The transition from piezoelectric crystals to ultrasound-on-a-chip technology has been particularly impactful, allowing for a single probe to emulate multiple different transducers through software-defined parameters. This versatility makes the devices indispensable for multidisciplinary teams that require various types of imaging throughout a single work shift.
Despite these significant technological advancements, the industry still faces several operational hurdles, such as limited imaging depth compared to larger, more powerful systems and a heavy dependency on the individual operator’s skill level. The quality of a medical diagnosis is often tied directly to the user’s proficiency, highlighting a massive and ongoing need for comprehensive clinician training programs. Ensuring that the influx of new, easy-to-use devices leads to accurate clinical results requires a significant investment in educational resources to mitigate the risk of diagnostic errors. Manufacturers are currently working to solve these issues by embedding automated quality indicators into their software, which provide real-time feedback to the user on image clarity and probe positioning. This focus on user-centric design is essential for moving the technology from a niche specialty tool to a ubiquitous diagnostic standard that can be safely utilized by nurses, paramedics, and general practitioners worldwide.
Market Leadership: Competition and Strategic Innovation
The competitive environment is currently a mix of established medical imaging giants and agile technology disruptors who are constantly pushing the boundaries of what is possible in a handheld format. GE HealthCare remains a dominant market leader with its focus on artificial intelligence integration and clinical versatility, while Butterfly Network has successfully disrupted the space with its semiconductor-based imaging architecture. These companies, along with other major players like Clarius Mobile Health and Philips Healthcare, maintain their competitive edge by focusing heavily on wireless connectivity, cloud compatibility, and significant cost reduction for the end user. The competition has led to a rapid cycle of innovation where new software updates frequently add significant diagnostic capabilities to existing hardware, extending the lifecycle of the devices and providing better value for healthcare facilities.
Other key players, including Siemens Healthineers, Fujifilm Sonosite, and Mindray Medical, continue to drive healthy competition by targeting specific clinical applications like anesthesia guidance or musculoskeletal imaging. These manufacturers are constantly innovating to improve image clarity and diagnostic precision in specialized fields, ensuring that handheld units can meet the rigorous demands of surgical and rehabilitative medicine. Their ability to balance high-end features with total affordability determines their success in capturing a larger share of the high-volume point-of-care market. As the sector matures, many of these leaders are forming strategic partnerships with software developers to create integrated ecosystems where ultrasound data is automatically synthesized with other patient health metrics. This holistic approach to medical data is making handheld ultrasound a foundational component of the modern electronic health record, ensuring that imaging data is accessible whenever and wherever a clinical decision needs to be made.
Strategic Integration: The Path Toward Connected Care
The long-term evolution of the handheld ultrasound market depended on the successful transition toward “intelligent” imaging and the broader Internet of Medical Things. As artificial intelligence algorithms became more sophisticated, they assisted doctors in interpreting complex images, effectively lowering the training barriers that previously limited the technology’s reach. This evolution allowed diagnostic data to flow seamlessly from rural clinics or a patient’s home directly into electronic health records, creating a more connected and responsive healthcare ecosystem. The integration of high-speed data networks ensured that high-resolution scans could be uploaded and analyzed by remote servers in seconds, providing clinicians with instant secondary opinions and automated diagnostic suggestions. This technological synergy transformed the handheld probe from a simple visualization tool into a powerful data acquisition device that supported evidence-based medicine at every level of care.
While large, cart-based systems were still required for complex, deep-tissue diagnostics and specialized surgical procedures, handheld devices came to dominate the point-of-care segment by the middle of the decade. The success of stakeholders in this industry was defined by their ability to provide the comprehensive educational support necessary to turn every healthcare provider into a competent user of this technology. As medical practice became more patient-centered and focused on immediate accessibility, these portable devices served as the primary diagnostic gateway for clinicians worldwide. The historical shift toward decentralized imaging was finalized as handheld units became standard equipment in medical schools, ensuring that the next generation of doctors viewed ultrasound as a fundamental part of the physical exam. This widespread adoption ultimately led to a more efficient healthcare system where diagnoses were made faster, costs were managed more effectively, and patient care was delivered with a higher degree of precision and empathy.