Supply chain vulnerabilities involving specialized medical-grade plastics and electronic sensors could potentially reduce the projected market growth rate from 6.67 percent to 5.17 percent. As the healthcare landscape evolves in 2026, the global pediatric medical devices market has established itself as a critical pillar of modern medicine, currently valued at approximately $39.75 billion. This specialized sector focuses on developing instruments and diagnostic tools specifically for the unique physiological requirements of infants, children, and adolescents, a demographic that was historically underserved by technology originally designed for adults. By 2034, the market is anticipated to reach $66.62 billion, fueled by a relentless drive toward miniaturization and more precise diagnostic capabilities. The current trajectory emphasizes that pediatric patients are not merely smaller versions of adults; their bodies possess distinct metabolic rates, varying organ maturity levels, and rapid physical growth patterns that necessitate bespoke engineering solutions. These factors create a high-stakes environment where innovation is not just preferred but essential for life-saving interventions in neonatal and pediatric intensive care units. As manufacturers navigate this complex landscape, they are increasingly integrating advanced materials and digital interfaces to ensure that medical equipment can keep pace with the dynamic development of a child’s body.
Core Drivers: The Impact of Miniaturization and Precision
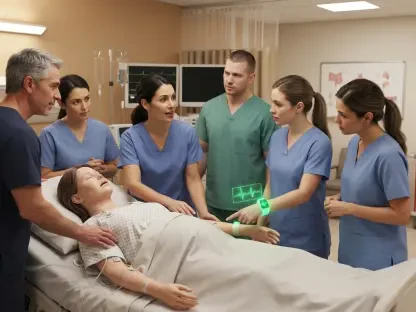
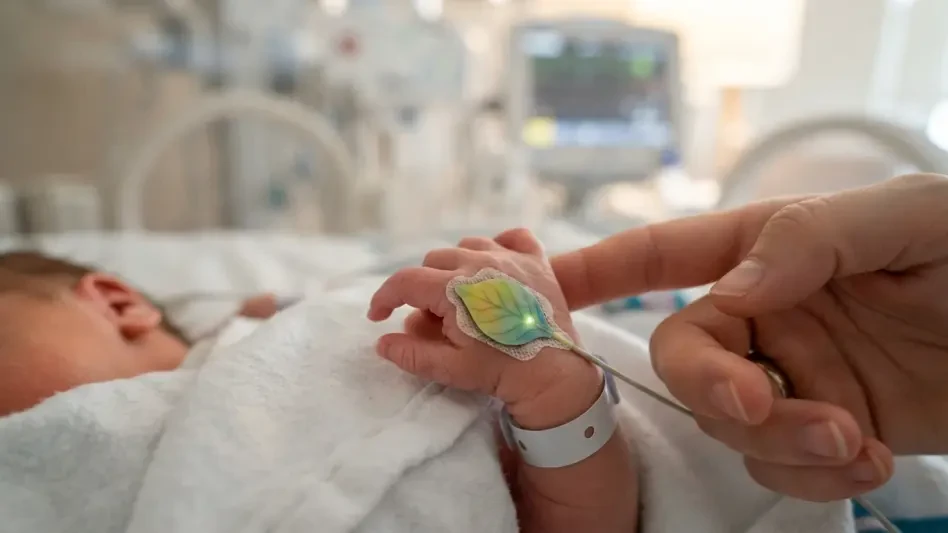
The push toward extreme miniaturization has revolutionized how neonatal intensive care units operate, allowing for higher levels of monitoring with significantly less physical impact on the patient. Traditional sensors and leads often posed risks to the paper-thin, fragile skin of premature infants, but the advent of medical-grade micro-sensors has changed this dynamic entirely. These devices now monitor vital signs like heart rate, oxygen saturation, and respiratory patterns through non-invasive or minimally invasive means, providing continuous data streams without the mechanical stress associated with older equipment. This shift is a primary catalyst for market expansion, as hospitals globally seek to upgrade their neonatal facilities to include “smart” monitoring systems that utilize specialized pediatric algorithms. Furthermore, the integration of wireless technology in these miniaturized sensors allows for greater mobility and facilitates skin-to-skin contact between parents and infants, which has been clinically proven to improve developmental outcomes. The engineering required to achieve this level of precision while maintaining high durability is a significant driver of both research and development spending and overall market value.
Beyond monitoring, precision in drug delivery and weight-based dosing has become a cornerstone of pediatric therapeutic interventions. Because children process medications at vastly different rates than adults, and because a minor dosing error can have catastrophic consequences for a toddler, the demand for sophisticated infusion pumps and delivery systems has surged. Current technology in 2026 focuses on low-volume infusion capabilities and integrated dose-limiting software that cross-references a child’s weight and age in real-time. These systems are designed to lock out potentially dangerous dosages, providing a critical safety net for healthcare providers in high-pressure environments. This necessity for weight-based accuracy extends into respiratory care as well, where ventilators must provide precisely calibrated tidal volumes to avoid lung injury in neonates. As more healthcare systems adopt these specialized delivery and ventilation platforms, the market continues to expand, driven by the realization that pediatric-specific technology is the only way to achieve the highest standards of safety and efficacy in young patients.
Structural Hurdles: Navigating the Pediatric Gap
One of the most persistent challenges facing the industry is the “pediatric gap,” a phenomenon where medical advancements for children often lag years behind their adult counterparts. This delay is largely rooted in the immense complexity of conducting clinical trials for a younger demographic, where patient populations for specific childhood diseases are often small and geographically dispersed. Furthermore, ethical considerations and the stringent requirements for parental consent create administrative layers that can slow the pace of device approval. In 2026, developers are forced to grapple with these extended timelines, which increase the financial risk associated with bringing a new pediatric device to market. To combat this, several regulatory bodies have introduced incentive programs and streamlined pathways for pediatric-only devices, but the inherent difficulty of recruiting enough participants for a statistically significant study remains a major barrier. This structural hurdle often results in “off-label” use of adult devices in children, a practice that, while sometimes necessary, carries risks that the industry is actively working to mitigate through more robust data collection and child-specific engineering.
The physical reality of a “moving target” further complicates the development and manufacturing of pediatric medical tools. Unlike an adult, whose physical dimensions and organ functions remain relatively stable, a pediatric patient undergoes rapid and significant changes from infancy through adolescence. A device that is perfectly suited for a newborn may be completely ineffective, or even dangerous, for a ten-year-old. This requires manufacturers to either create an extensive range of sizes for every product or develop highly adjustable, modular systems that can accommodate a wide spectrum of physical growth. This need for high specialization and versatility naturally leads to higher manufacturing costs and more complex supply chain requirements. Moreover, the specialized plastics and electronic components needed for these devices must meet rigorous biocompatibility standards, adding another layer of difficulty to the production process. When supply chain disruptions occur, as noted in recent market analyses, the impact is felt more acutely in this sector because there are often few alternatives for these highly specific, medical-grade components.
Strategic Opportunities: Growth Adaptive and Emergency Solutions
A significant frontier of innovation in 2026 involves the development of growth-adaptive prosthetic devices and orthopedic implants. For decades, children with limb differences or those requiring surgical implants faced a grueling cycle of frequent replacement surgeries as their bodies outgrew their medical hardware. This not only placed a heavy financial burden on families but also subjected children to repeated physical trauma and long recovery periods. The emergence of modular prosthetic systems and adjustable internal implants is changing this narrative. These new designs utilize telescoping components and adjustable sockets that can be modified non-invasively or through minimally invasive procedures as the child grows. By extending the lifespan of a single device, these technologies improve the quality of life for the patient and offer a more sustainable economic model for healthcare payers. The market for these adaptive technologies is expected to grow as material science continues to produce stronger, lighter, and more flexible materials that can mimic the natural movements of a developing musculoskeletal system.
In tandem with long-term adaptive care, there is a burgeoning market for pediatric-specific disaster response and emergency medical equipment. Historically, emergency responders and field hospitals have been primarily equipped with adult-sized tools, which can be difficult to use effectively on small children during crises. There is now a concerted global effort to bridge this gap by producing portable pediatric airway kits, child-sized immobilization devices, and portable infant warming systems designed for use in the field. These products are being integrated into national stockpiles and humanitarian aid kits, recognizing that children are often the most vulnerable population during natural disasters or public health emergencies. This expansion into the emergency and pre-hospital space represents a major strategic opportunity for manufacturers who can produce rugged, intuitive, and highly portable versions of standard pediatric hospital equipment. The demand is particularly high for devices that do not require constant access to a power grid, favoring the development of high-capacity battery-powered monitors and mechanical ventilation tools that can operate in challenging environments.
Cardiovascular and Respiratory Interventions: Vital Focus Areas
Congenital heart defects remain a leading cause of infant mortality, making the cardiology segment one of the most vital areas for technological investment. The anatomy of an infant’s heart is incredibly delicate, and performing interventions requires instruments that are both exceptionally small and highly precise. In recent years, there has been a notable surge in the development of specialized stents and valves designed specifically for neonatal and infant use. For instance, the creation of micro-stents that can be delivered via catheter to repair cardiac anomalies in newborns has significantly reduced the need for open-heart surgery in the first weeks of life. These interventions are often life-saving and represent some of the most sophisticated engineering in the entire medical device industry. Investors have taken notice, pouring significant capital into startups and research initiatives focused on pediatric cardiology. This influx of funding is accelerating the transition from experimental designs to commercially available products, which is a major contributor to the projected $66 billion market valuation.
Respiratory health is another pillar of the pediatric market, particularly as healthcare providers work to manage the long-term effects of premature birth and rising rates of childhood asthma. Neonatal ventilators have become highly advanced, incorporating sophisticated sensors that can detect a premature infant’s own breathing efforts and provide synchronized support that minimizes lung strain. Beyond the hospital setting, the market for pediatric-specific inhalers and nebulizers is expanding as these devices are redesigned to be more user-friendly for young children. Many modern nebulizers now feature designs that are less intimidating and quieter, which helps improve compliance among pediatric patients. Furthermore, the integration of digital tracking in these devices allows parents and doctors to monitor usage patterns and respiratory health trends via mobile applications. This shift toward “connected” respiratory care is creating a more holistic approach to managing chronic conditions, ensuring that pediatric patients receive the right level of support both in and out of the clinical environment.
Segment Analysis: Diagnostics and End-User Shifts
The in vitro diagnostic (IVD) segment currently commands the largest share of the pediatric medical devices market, accounting for more than 21 percent of the total value. This dominance is largely due to the critical role that early screening plays in neonatal health. Immediately following birth, infants are routinely screened for a wide array of genetic disorders, infections, and metabolic imbalances that require immediate intervention. The tools used for these screenings, ranging from blood gas analyzers to advanced genetic testing platforms, are essential for identifying conditions that might not be physically apparent at birth. As diagnostic technology becomes more sophisticated, the speed and accuracy of these tests continue to improve, allowing for even earlier detection and treatment. This segment remains a steady source of revenue for the industry, as newborn screening is a mandated health practice in many nations, ensuring a consistent and growing demand for high-quality diagnostic consumables and hardware.
While hospitals remain the primary end users of pediatric medical devices, there is a notable shift toward ambulatory surgical centers (ASCs) and specialized pediatric clinics. Hospitals still account for over 57 percent of the market because they house the specialized intensive care units and surgical suites required for complex pediatric cases. However, the trend toward performing minor surgeries and diagnostic procedures in outpatient settings is gaining momentum. This shift is driven by a desire to reduce the psychological stress on children, who often find large hospital environments intimidating, and to lower overall healthcare costs. ASCs are increasingly investing in pediatric-specific equipment, such as smaller surgical instruments and child-sized anesthesia delivery systems, to cater to this growing patient base. This decentralization of pediatric care is creating new sales channels for manufacturers and encouraging the development of more portable and cost-effective devices that can be utilized in smaller, specialized facilities without sacrificing the quality of care.
Regional Insights: Innovation Hubs and Emerging Engines
North America continues to hold the largest share of the global pediatric medical devices market, currently sitting at approximately 38.55 percent. This leadership is sustained by a robust healthcare infrastructure and significant government investment in pediatric research. In the United States, initiatives designed to foster innovation in pediatric medical technology have created a collaborative ecosystem between academic institutions, private developers, and regulatory agencies. These programs are specifically aimed at bridging the gap between an initial invention and its ultimate commercialization, providing the necessary funding and guidance to navigate the complex approval process. Additionally, healthcare policies in the region often emphasize early screening and preventive care, which drives high utilization rates for diagnostic and monitoring tools. The presence of many of the world’s leading medical device manufacturers in the region further solidifies its position as a primary hub for pediatric technological advancement.
In contrast, the Asia-Pacific region is characterized by its rapid growth, emerging as a major engine for the global market with an expected compound annual growth rate exceeding 8 percent. In nations like India and China, the expansion of healthcare access and a growing middle class are driving demand for advanced pediatric care. The Chinese government has been particularly aggressive in establishing national and regional children’s medical centers, creating a massive requirement for high-end diagnostic imaging and neonatal monitoring equipment. Similarly, the Indian government has introduced policies to encourage the domestic manufacturing of medical devices, aiming to make life-saving technology more affordable for its large pediatric population. In Japan, the regulatory environment is being adjusted to provide more support for pediatric device reviews, further incentivizing international manufacturers to enter the market. These regional developments suggest that while North America remains the current leader, the long-term growth of the industry will be increasingly influenced by the expanding healthcare sectors in Asia.
Future Strategic Considerations: Redefining Pediatric Healthcare
The integration of artificial intelligence and machine learning into pediatric monitoring systems has already begun to redefine the standards of care in intensive care environments. By analyzing vast amounts of physiological data in real-time, these AI-driven platforms can distinguish between normal growth-related changes and the subtle early signs of clinical deterioration. This capability is particularly valuable in pediatric care, where a child’s condition can change with alarming speed. Looking forward, the development of these “smart” systems will likely become the industry standard, providing clinicians with predictive insights that allow for proactive rather than reactive treatment. This shift toward predictive medicine will necessitate a new strategic approach for manufacturers, focusing on software-as-a-service models and continuous data integration alongside traditional hardware sales. The ability to offer comprehensive digital solutions that enhance the utility of physical devices will be a key differentiator in the competitive landscape of the next decade.
The pediatric medical devices market has successfully transitioned into a stand-alone sector that demands specialized engineering and unique regulatory considerations. To maintain this momentum, stakeholders must prioritize the development of adaptive materials and decentralized diagnostic tools that can meet the needs of a global and diverse patient population. The progress made in miniaturization, cardiovascular intervention, and growth-adaptive technology has provided a solid foundation for the significant market expansion projected through 2034. As healthcare systems globally continued to prioritize maternal and child health outcomes, the industry successfully navigated the complexities of specialized production and clinical validation. Moving forward, the most successful entities will likely be those that can demonstrate long-term clinical efficacy while reducing the total cost of care through innovation. The focus has firmly shifted toward creating a healthcare environment where technology truly grows with the child, ensuring that the youngest patients have access to the same level of innovation as the adult population.